For years, the IP networking and optical transport industries evolved along separate disaggregation trajectories. IP networking disaggregated first: white-box switches and open NOS platforms emerged for data center and SP routing use cases. Optical transport lagged, remaining proprietary and vertically integrated. But shared goals, technical innovations in coherent optics, and operator cost pressure are now aligning these two segments.
This analysis draws on findings from the "Open and Disaggregated Packet and Optical Networks Market Leadership Study", a comprehensive operator survey conducted by Heavy Reading in collaboration with IP Infusion, Telecom Infra Project (TIP), Infinera, and Volta. The study represents one of the most comprehensive assessments of operator attitudes toward open packet and optical network disaggregation.
Key Survey Findings
Operators Are Ready to Move
The survey found that a significant majority of network operators are either actively evaluating or planning to deploy disaggregated packet and optical network solutions within 24 months. The primary drivers cited were cost reduction, vendor independence, and architectural flexibility, the same set of drivers that previously accelerated IP disaggregation in data centers.
IP and Optical Convergence Is the Goal
A strong majority of survey respondents identified IP-optical convergence (collapsing separate IP and optical management into a unified platform) as a strategic priority. This aligns directly with the IPoDWDM architecture that OcNOS supports: IP routing and coherent optical management in a single NOS, single CLI, and single management system.
The Biggest Barrier: Ecosystem Maturity
The most frequently cited barrier to adoption was ecosystem maturity: specifically, concern about whether a sufficient ecosystem of validated hardware, software, and integration partners existed to make production deployment practical. This concern is addressable: OcNOS's 40+ qualified hardware platforms, MEF 3.0 certification, TIP IPoDWDM PoC completion, and 900+ production deployments directly address ecosystem maturity concerns.
The Convergence Accelerators
Three technical developments are accelerating the convergence of IP and optical disaggregation:
- ZR/ZR+ coherent optics as standard pluggables: 400G ZR+ transceivers that plug into standard QSFP-DD ports have eliminated the need for dedicated transponder hardware, making optical integration into IP routers practical
- Open OLS (Optical Line Systems): standardized APIs for optical line system control (TAPI, OpenConfig optical) enable vendor-neutral management of the optical amplification and switching layer
- Unified NOS with optical management: OcNOS 7.0 manages both IP routing and coherent optical interfaces from a single platform, operationally realizing the convergence that the survey identified as a strategic goal
IP Infusion Marketing Team
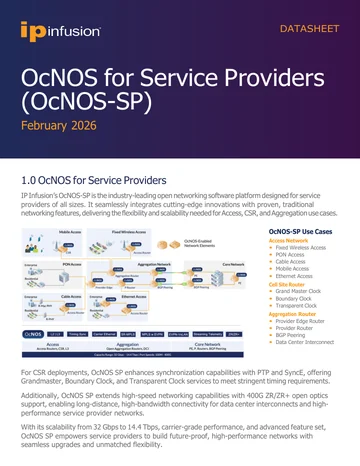
OcNOS-SP 数据手册
表单简短。提交后您的 PDF 将立即在新标签页中打开。
✓ 正在新标签页中打开您的 PDF……
如果未能自动打开,请使用下方链接。
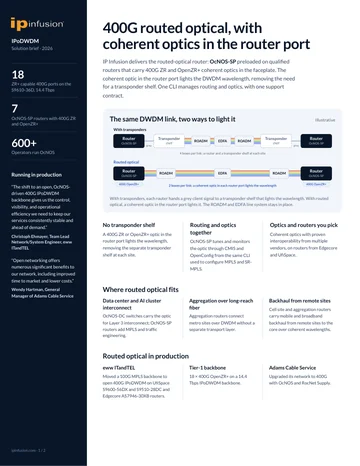
采用 400G OpenZR+ 的 IPoDWDM
表单简短。提交后您的 PDF 将立即在新标签页中打开。
✓ 正在新标签页中打开您的 PDF……
如果未能自动打开,请使用下方链接。
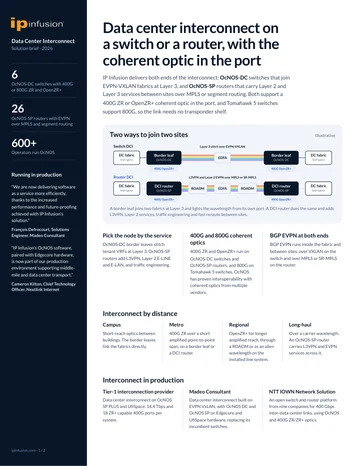
数据中心互联解决方案简介
表单简短。提交后您的 PDF 将立即在新标签页中打开。
✓ 正在新标签页中打开您的 PDF……
如果未能自动打开,请使用下方链接。